
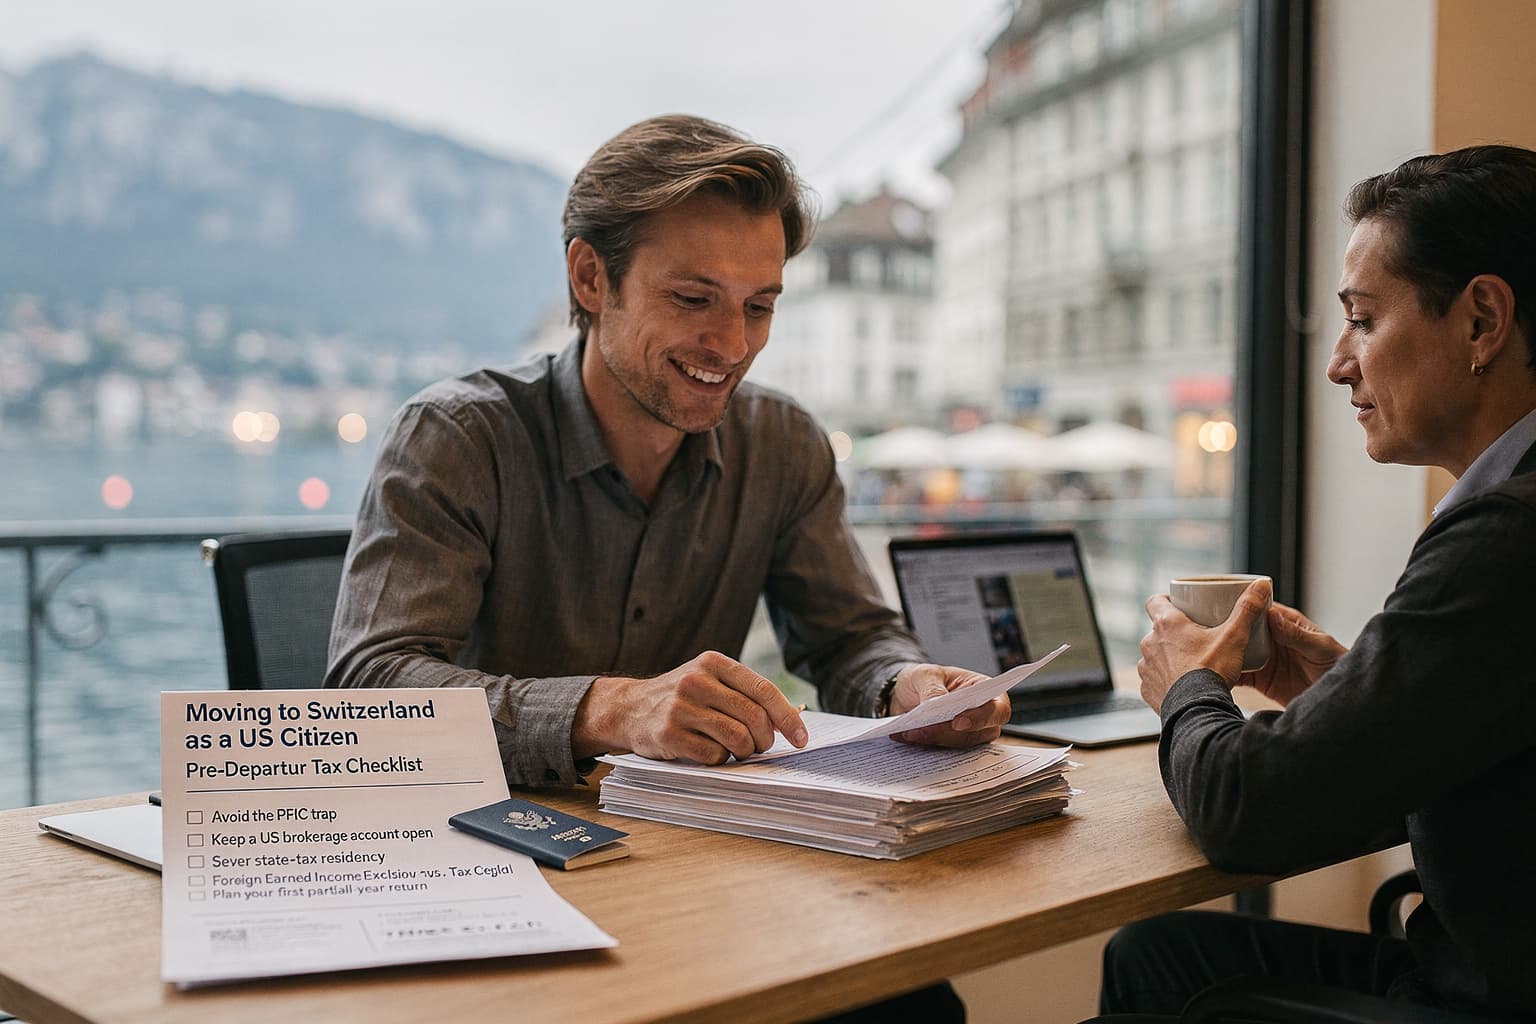
Four Tax Moves to Make Before You Board
You don't need to become a tax expert before moving to Switzerland, but four decisions made in the right order will save you more money and anxiety than almost anything else. Think of this as pre-departure hygiene: none of it is complicated, but skipping a step has asymmetric costs.
- Decide your FEIE vs Foreign Tax Credit election before your first Swiss payday
- Avoid the PFIC trap by keeping investments US-domiciled
- Settle your US brokerage account while you still have a US address
- Sever your last state's tax residency in the calendar year you leave
1. Decide your FEIE vs Foreign Tax Credit election before your first Swiss payday
The Foreign Earned Income Exclusion (FEIE) lets you exclude foreign wages or salary from US taxable income. For 2026, the maximum exclusion is $132,900 per qualifying person, with a housing exclusion or deduction capped at $39,870. The IRS spells this out in Figuring the foreign earned income exclusion (2026).
The FEIE is elective, not automatic. You choose it by filing Form 2555 with a timely filed return or an amended return under specific rules. The Foreign Tax Credit (FTC) is a dollar-for-dollar credit for Swiss income taxes you pay, so you don't get taxed twice on the same money. Since Switzerland's income tax is generally higher than US tax on the same income, many Americans in Switzerland are better off using the Foreign Tax Credit instead of, or in addition to, the FEIE. This is the single most important pre-departure election; read our FEIE vs Foreign Tax Credit: The Switzerland Decision Guide for Americans for a full walkthrough.
$132,900
2026 FEIE maximum exclusion
2. Avoid the PFIC trap before it starts
A Passive Foreign Investment Company (PFIC) is a foreign pooled investment, most UCITS funds, European ETFs, unit-linked insurance and many Swiss mutual funds. If you hold one, you face punitive US tax rules and a separate Form 8621 for each PFIC, each year. A US-domiciled ETF like VTI, VOO or VXUS is a US corporation and can never be a PFIC. The rule applies whether you live in Ohio or Zurich, so the trap is simply: don't buy European or UCITS funds once you arrive; keep investing US-domiciled. Our Swiss Mutual Funds, ETFs and the PFIC Tax Trap: What US Expats Must Know explains the plain-English version.
3. Settle your US brokerage account while you still have a US address
Many US brokers restrict or close accounts once you report a foreign address. Fidelity does not open new accounts for non-US residents and limits existing ones; Vanguard and Merrill generally refuse new overseas accounts. Charles Schwab routes foreign residents to Schwab One International, and Interactive Brokers accommodates Americans abroad. Open or keep the US brokerage account before you leave, and keep a legitimate US mailing address for statements and two-factor authentication. A US brokerage account is a US account, it is not a foreign account for FBAR (Report of Foreign Bank and Financial Accounts, FinCEN Form 114, filed if you have more than $10,000 aggregate in foreign accounts) or Form 8938. A Swiss brokerage account you open later does count toward those thresholds. For a broker-by-broker rundown, see Forbes Finance Council (Aug 2026).
Don't play address games
Giving a relative's US address to conceal that you live abroad is a false statement and can itself trigger account closure. Use a firm whose rules fit, not a workaround.
4. Sever your old state tax residency in the calendar year you leave
Your old state can still tax you after you move if you don't properly sever domicile. Domicile is the one place you treat as your permanent home, physical presence plus intent. To change it, you must both leave the old state and land in a new one; the burden of proof is on you. Aggressive states like New York and California pursue departing residents. Practical steps include surrendering your driver's license, changing voter registration through FVAP, selling or renting your home at arm's length, closing state-only bank accounts, filing a part-year resident return stating your departure date, and keeping records like a travel calendar, foreign lease and utility bills. The Tax Adviser, "Changing domicile from a high-tax state to a low-tax state" (Dec 2024) summarizes the leave-and-land rule.
Your First Partial-Year Return, Without the Panic
For the year you move, you will generally file a US return on your worldwide income, but you may be eligible for the FEIE or FTC for Swiss-earned wages after you arrive. The mechanics are manageable: choose your election on Form 2555 or Form 1116 with your timely filed return. If you need to revoke the FEIE later, attach a statement to the return for the first year you don't want it, but once you revoke, you generally cannot re-claim it for the next five tax years without IRS approval. That's an election decision, not a moral judgment.
What Not to Panic About
- FBAR and FATCA are information reports, not automatic tax; being compliant is routine once you know your thresholds.
- The US-Switzerland totalization agreement generally prevents paying US Social Security and Swiss AHV/IV on the same earnings, it addresses social security, not income tax.
- If you find a past mistake, there is a constructive path forward; it's fixable, not a catastrophe.
If you're already thinking about the eventual return, use our Moving Back to the US from Switzerland: Your Tax and Money Timeline to plan the reverse move.
This article is educational, not individual advice. The right election, brokerage setup and state facts depend on your situation. We're specialists for Americans in Switzerland, both systems under one roof, and we help you make these calls before you board. If you want a second set of eyes on your pre-departure plan, get in touch.